If you are living with kidney failure, dialysis, or the possibility of a transplant, health coverage is more than paperwork—it is part of your care plan. Medicare can cover many essential services, but the coverage path you choose can affect how you access doctors, dialysis facilities, hospitals, and prescription medications. The goal is to understand your choices well enough to select coverage that fits your medical needs and comfort level.
At Green Bee Insurance, we help people in Fort Lauderdale and across South Florida make Medicare decisions with clarity, especially when ongoing care makes the details matter.
Medicare Can Cover Important Kidney Care Services
For people with permanent kidney failure, Medicare can help cover dialysis and transplant-related care when eligibility requirements are met. Original Medicare generally uses Part A for inpatient hospital care and Part B for outpatient dialysis, physicians’ services, certain dialysis supplies and services, and many transplant-related services.
That is reassuring, but it is important to remember that “covered” does not always mean every cost is fully paid. Deductibles, coinsurance, prescription drug coverage, provider participation, and plan rules can all affect what you pay and how you receive care. Your individual situation may also involve employer coverage, retiree coverage, Medicaid, or other benefits that coordinate with Medicare.
The Decision Is About How You Want Coverage to Work
For many people, the main decision comes down to two broad approaches: staying with Original Medicare and adding coverage to help with out-of-pocket expenses, or enrolling in a Medicare Advantage plan that provides Medicare benefits through a private insurer.
Neither approach is automatically right or wrong. The better fit depends on the care team you rely on, where you receive dialysis, the medications you take, your travel habits, and how much flexibility you want when choosing providers.
Medicare plan counseling should focus on the details of your real life—not just a brochure or a monthly premium. If you already have specialists, a preferred dialysis center, or a transplant team, those relationships should be part of the conversation from the start.
Original Medicare With Supplemental Coverage
Original Medicare lets you see any doctor or facility that accepts Medicare, without needing to stay within a private plan’s provider network. Many people value that flexibility, particularly when they are receiving specialized treatment or may need care in more than one location.
A Medicare Supplement Insurance policy, often called Medigap, may help pay some of the costs that Original Medicare does not pay on its own. Prescription drug coverage is typically handled separately through a Medicare Part D plan. This approach can offer a more predictable structure for some people, but plan availability, eligibility, premiums, and benefits vary. It is important to review the options available to you before making a decision.
For a person receiving dialysis or preparing for a transplant, this path may be appealing when broad provider access is a top priority. It can also be useful for someone who wants the freedom to seek care from Medicare-participating providers without relying on a local network.
Medicare Advantage Coverage
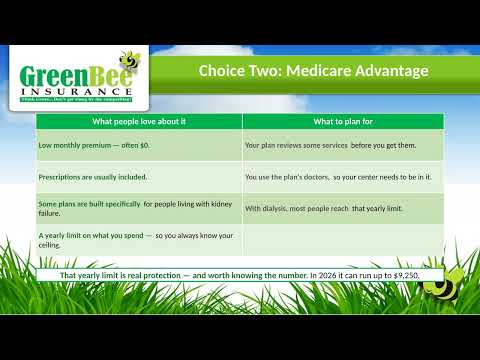
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They must provide at least the same basic Medicare-covered benefits as Original Medicare, but they may use provider networks, prior authorization rules, copayments, and plan-specific formularies for prescription drugs.
For some beneficiaries, a Medicare Advantage plan can be a convenient all-in-one arrangement that includes medical and prescription drug coverage. These plans may also offer extra benefits that Original Medicare does not include. However, the plan’s network and coverage rules deserve close attention when care is complex or ongoing.
If you are receiving dialysis, seeing a nephrologist, or working with a transplant center, confirm that the providers and facilities you depend on participate in the plan. Ask how the plan handles referrals, authorizations, outpatient treatment, hospital care, and the medications your care team has prescribed. A plan that looks attractive on paper may not be the right fit if it disrupts important relationships in your care.
Prescription Coverage Should Never Be an Afterthought
Medication coverage can be especially important for people managing kidney disease. Some drugs and dialysis-related medications may be covered under Part B in certain circumstances, while other prescriptions may fall under Part D or a Medicare Advantage plan’s drug benefit.
That is why a careful review should include your current medication list, the pharmacies you prefer, and any medications your doctors expect you may need. A Medicare Part D review is not simply about whether a drug appears on a list. It should also consider coverage restrictions, pharmacy options, and how the plan treats the prescriptions that matter most to you.
Questions to Ask Before You Enroll
A meaningful Medicare review should give you practical answers. Before choosing coverage, consider asking:
- Can I keep my kidney doctor, dialysis center, hospital, and transplant team?
- How does this option cover the services I receive most often?
- Are my prescriptions covered, and are there special rules for filling them?
- Will I need referrals or prior authorization for important services?
- What happens if I need care while traveling or away from South Florida?
- How could this choice work alongside any employer, retiree, or other health coverage I have?
These questions can turn a confusing Medicare conversation into a clear comparison. They also help prevent a decision from being based solely on advertisements, general recommendations, or assumptions about what a plan includes.
Get Personal Medicare Guidance Before You Decide
When your health care needs are ongoing, the right Medicare choice should support—not complicate—your treatment. Green Bee Insurance provides Medicare guidance services designed to help you compare your options in a straightforward, pressure-free way. We can help you review how your doctors, dialysis facility, hospital, and medications may fit with the coverage choices available to you.
There is no need to sort through every plan detail alone. A thoughtful review can help you move forward with more confidence and a better understanding of what questions to ask.
FAQ
Does Medicare cover dialysis?
Medicare can cover many dialysis-related services and supplies for eligible individuals with permanent kidney failure. Coverage and what you pay can vary based on whether you have Original Medicare, a Medicare Advantage plan, or other insurance.
Does Medicare cover kidney transplants?
Medicare can cover many transplant-related hospital and physician services when the care is received through eligible providers and facilities. Coverage for medications and follow-up care depends on the circumstances and the type of Medicare coverage you have.
Should I choose Medicare Supplement insurance or Medicare Advantage?
The answer depends on your providers, facility access, prescription needs, budget preferences, and comfort with network and authorization rules. A side-by-side review can help clarify which approach best fits your situation.
Can I keep my current kidney doctor?
It depends on the coverage you choose and whether your doctor participates in that coverage. Before enrolling, verify your nephrologist, dialysis facility, hospital, and other specialists directly with the plan and provider.
Can Green Bee Insurance help me compare Medicare options?
Yes. Green Bee Insurance offers friendly Medicare plan counseling for people in Fort Lauderdale and throughout South Florida who want help understanding their options and checking how their care team and medications may fit with available coverage.